Hello, this is Ryuta Hamamoto from TIMEWELL.
90.7% of small Japanese suppliers had a price negotiation this year. That figure comes from a survey the Small and Medium Enterprise Agency sent to 300,000 firms, with 69,625 responding.
Only 54.2% of the cost increase actually passed through. By category: 55.7% for raw materials, 50.0% for labour, 48.9% for energy1.
Put those two numbers side by side and the problem moves. Getting a meeting is no longer the issue. What you say in it is.
This piece walks through how to prepare, based on reading the JFTC guideline and the SME Agency handbook in the original. There is a working Excel at the end.
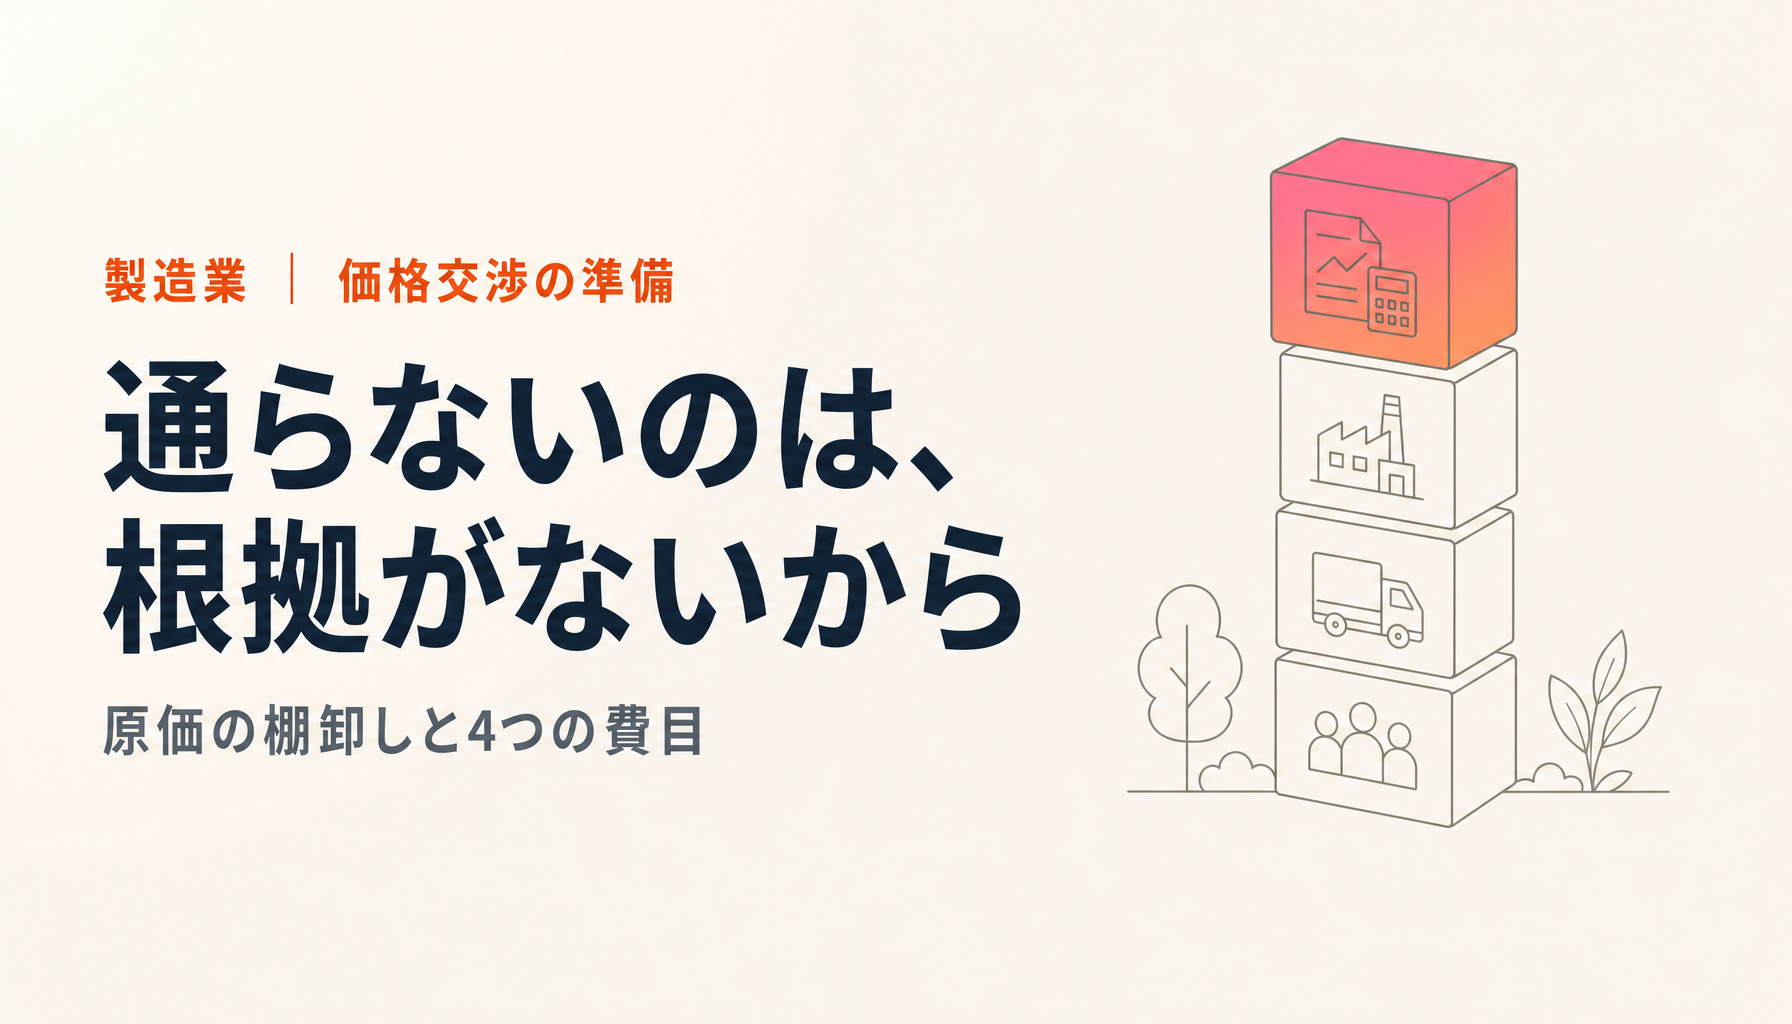
Split costs four ways, and keep labour on its own
Start by dividing your costs into four:
- Raw materials (stock, purchased parts)
- Energy (electricity, gas, fuel)
- Labour (scheduled increases, base pay revisions, statutory benefits)
- Other (depreciation, storage, freight, subcontracting)
I did not invent this. The Japan Fair Trade Commission and the Cabinet Secretariat published a guideline on passing through labour costs, and its attached template uses exactly these four2. This is the national default.
Why split them? The SME Agency handbook is direct about it: labour costs in particular should be negotiated separately from materials and energy3.
Anyone who has sat in these meetings can guess why. Present one number — "our costs went up 20%" — and the buyer negotiates against the total. The line they push on is labour. A materials increase comes with a supplier's letter attached. A wage increase comes with nothing but your word, and gets met with "we're all working hard."
The category-level pass-through rates bear this out. Labour sits near the bottom at 50.0%. And among firms that passed through nothing at all, 16.6% were on materials against 20.6% on labour1.
You cannot negotiate what you have not costed
To split your request four ways, you need your own costs split four ways. This is where most firms stop.
The SME Agency handbook says so plainly:
Firms can calculate expenses and labour costs at the company or business-unit level, but costing per product or per service is highly complex, and many are unable to do it. This has become one of the factors that makes price negotiation difficult.3
The same page carries quotes from the field. "We have been taking machining work at the same unit price for nearly twenty years. We have never costed it by part or by process" (parts machining). "We have never calculated cost by route based on measured time and distance" (freight)3.
None of that is surprising. What stopped me was the next page.
On how to actually do the costing, the handbook offers a diagram titled "Search examples for cost accounting." Its advice is to type "cost accounting" plus a difficulty level, a tool type and your industry into a search engine. Try "cost accounting, simple, recommended app, trucking," it suggests4.
On the one thing the government has identified as blocking negotiations, there is no official tool. Trucking gets a calculation sheet from the national trucking association. Everyone else is told to go and look.
The JFTC does have a template. But it is a blank Word form: the category boxes are there, the arithmetic that fills them is not2.
So there is a form that says "break it down by category," and nothing that says how to build each category. That gap is the subject of this article.
I have written about building up machining cost itself in cost accounting for manufacturers with AI, and about process time and charge rates in calculating machining time. This piece picks up after that: turning a cost figure into a negotiation.
Struggling with AI adoption?
We have prepared materials covering ZEROCK case studies and implementation methods.
Do not hand over your cost sheet
This was the part of the original text that surprised me most.
Under "actions suppliers should take," the guideline says:
This does not deny a supplier's own judgment to show its labour cost position to the buyer. However, disclosing one's cost structure including labour costs to the buyer may conversely result in the buyer auditing those costs and demanding cost reductions.2
It then directs suppliers to use published data as evidence — material whose determination process involved the relevant parties and which reflects economic reality. Specifically: prefectural minimum wages and their rate of increase, settlements from the spring wage negotiations, the Ministry of Land, Infrastructure and Transport's labour rates for public works, and standard freight rates for general trucking2.
The same passage notes that pass-through is sometimes granted with no supporting documents at all, and sometimes without disclosing any of the supplier's own labour cost information2.
The more honest you are by instinct, the more you want to show the full breakdown. "Look, I am opening the books, now trust me." I understand the impulse. But it puts you on their ground. You become the party being audited.
So: cost yourself out for your own benefit, and present a number grounded in public indicators. Separate the paper you keep from the paper you send. That is the single most important line to draw here.
On how value engineering requests turn into discount demands, I wrote separately in why VA/VE turns into a discount request. That piece is about defining cost; this one is about what to do once you have.
Four ways to build the number
So what do you ask for? The guideline gives real examples, named by industry. They fall into four patterns.
Link it to a published indicator. Tie your request to the minimum wage increase or the revision to public works labour rates. The guideline describes a non-ferrous metals manufacturer that sorted its products into "no price revision for thirty years" and "no price revision for twenty years," then sought increases against the minimum wage rise for each bracket. A building maintenance firm seeks an increase matching its prefecture's minimum wage rise at every April contract renewal2.
This is the pattern most likely to land. The buyer can look at the same number, so the argument shifts from "did costs rise" to "which index applies."
Build it up from actual costs. Add up what has increased, or what you expect to. A general machinery manufacturer calculates the rise in labour, materials and energy for each order. The example I liked most: a technical services firm that had only ever quoted for on-site hours, and started quoting travel time as well2. Beginning to charge for something you were absorbing is a negotiation in its own right.
Decide the number first, then find the evidence. Work back from the deficit you need to close or the pay rise you need to fund, set the figure, and gather support afterwards. It looks backwards, but it is in the guideline: a ceramics manufacturer calculated the unit price needed to eliminate a loss-making division's deficit, then cited equal-pay compliance and the minimum wage increase as grounds2.
Include your own suppliers' labour costs. Not just your wages, but those of your subcontractors. The guideline requires this explicitly, and the template repeats it: consider labour costs at your own suppliers and theirs. One logistics services firm passed the exact increase its subcontractor requested straight through to its buyer2.
My own view: the first and fourth combine well. Set the overall level with a public indicator, then add subcontractor increases as a hard number. The first is hard to argue with, and the second is not your own doing, so neither is an easy target for auditing.
Go first
One more thing the guideline states plainly.
Do not wait to be given a price. Put your number forward. The reasoning is spelled out: the buyer usually holds the stronger position, and once they have named a figure, asking for more than that — let alone getting it — becomes very difficult2.
On timing, it lists examples. Before the buyer sets next year's budget. At a scheduled price revision or contract renewal. Once the direction of the minimum wage increase is known. After public works labour rates are revised. At the annual productivity meeting. During the buyer's busy season2.
The thread running through all of them is the same: move before the decision is locked, or when your leverage is relatively strong. Raise it after the budget is set and you get "there's no room this year."
There is an encouraging way to read that 90.7%: at least once a year, there is a conversation. The question is whether you walk into it with something prepared.
The template
I have put all of this into one Excel file, the price negotiation package.
It has four working sheets, and they are deliberately split between internal and external use.
① Cost inventory (internal) takes the same four categories and returns your cost per unit. ② Target price (internal) puts your current price next to that cost and returns whether you are underwater, plus the unit price, percentage increase and annual impact needed to hit your target margin.
③ Building the request lays out the four patterns above so you can pick the ones that fit, with the calculation for the indicator-linked approach built in. Note that it multiplies by labour's share of total cost — apply the index to your whole price and you will overshoot.
④ Negotiation request form (external) is the paper you actually send, laid out to match the JFTC attachment.
Sheets ① and ② are marked internal because of the warning above. They exist so you know what you need, not so the buyer can audit you.
There is also a sheet listing usable public sources with links. Minimum wages are revised every October, so pull the current figure before you negotiate.
The download link is below this article.
Where a system helps
A brief word about our own product.
The heaviest part of this work is not the negotiation. It is everything before it. When did this item's price last change? What did we quote for it? What did we charge for a similar part? When did the subcontractor last ask for an increase? Most firms reassemble this every time from paper, spreadsheets and memory.
Our enterprise AI, ZEROCK, is built to hold past drawings, quotations and actual costs as structured, connected data inside your company. It is encrypted on AWS servers in Japan, and customer drawings are never used to retrain models.
One honest caveat on sequence. Connect the data before the cost categories are defined and you get a wall of numbers nobody can read. Fix the form and the categories first. The system comes after.
In short
- 90.7% get the negotiation. 54.2% gets through. The bottleneck is evidence, not access
- Split into four categories and keep labour separate. Bundled, labour is what gets cut
- The SME Agency says poor per-product costing blocks negotiations, then tells firms to search the internet for a costing tool
- Do not hand over your cost sheet. The guideline warns it invites a cost audit
- Present a figure built on published data: minimum wages, spring wage settlements, public works labour rates, standard freight rates
- Four ways to build it: indicator-linked, cost build-up, target-first, and including your suppliers' labour
- Go first. Before the budget closes, at renewal, once the minimum wage direction is known
If I had to pick one thing to do on Monday: count how many lines on your own quotation sheet have not been updated since last year. That is the first piece of homework.
For help preparing a negotiation, or connecting cost and drawing data so it stays in your company, get in touch.
References
Footnotes
-
Results of the follow-up survey for the March 2026 Price Negotiation Promotion Month (Small and Medium Enterprise Agency, published 26 June 2026). Share of firms that had a price negotiation 90.7%, pass-through rate 54.2%, by category (materials 55.7%, labour 50.0%, energy 48.9%), public procurement 48.4%, 300,000 firms surveyed with 69,625 responses, fieldwork 20 April to 3 June 2026 ↩ ↩2
-
Guideline on Price Negotiations for the Appropriate Pass-Through of Labour Costs (Cabinet Secretariat and Japan Fair Trade Commission, 29 November 2023). The four-category split in the attached request template, the actions suppliers should take, the warning on disclosing cost structure, the list of published sources, the worked examples for setting a request, and the timing examples all come from this guideline ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7 ↩8 ↩9 ↩10 ↩11
-
Price Negotiation Handbook for Small and Medium Enterprises, revised edition (Small and Medium Enterprise Agency, first issued March 2022, last revised January 2026), Check 3 on cost accounting and Check 5 on quotation templates ↩ ↩2 ↩3
-
Same handbook, p.14, "Search examples for cost accounting." It suggests adding difficulty, tool type and industry keywords to a search for "cost accounting," and for trucking points to the MLIT guide and the Japan Trucking Association's calculation sheet ↩