Hello, this is Ryuta Hamamoto from TIMEWELL.
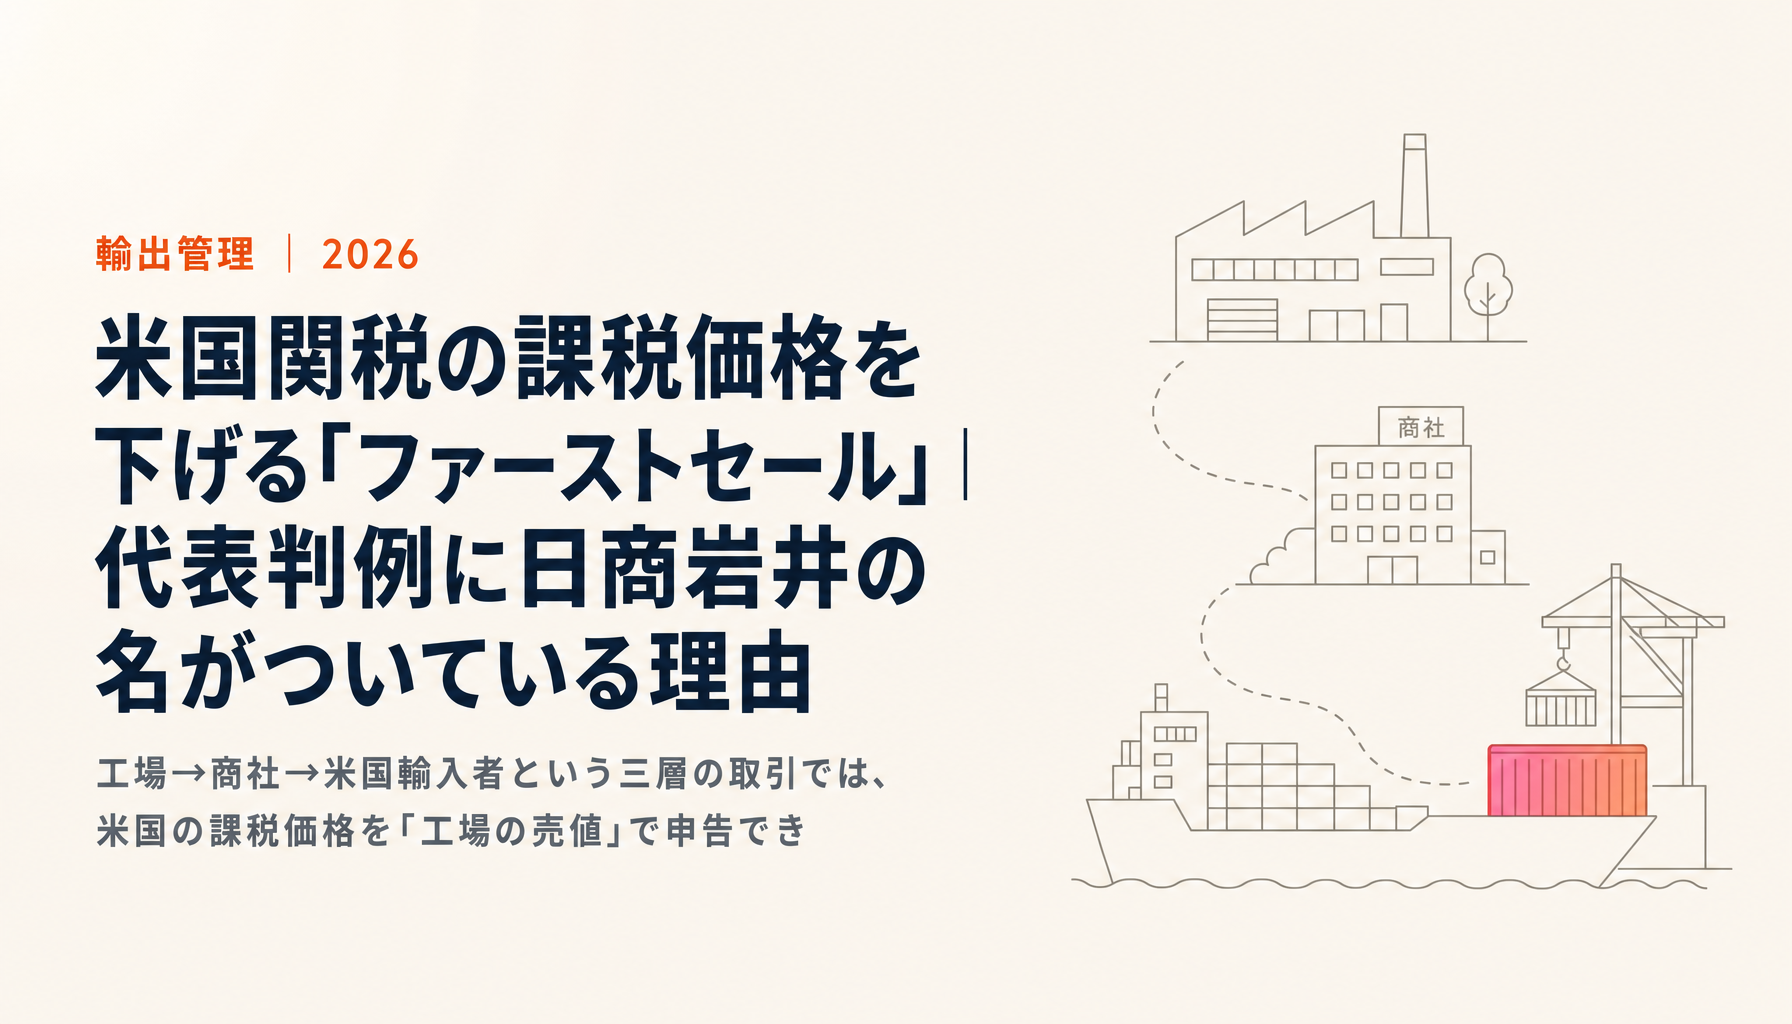
There is a technique in U.S. customs practice called first sale. The leading case is Nissho Iwai American Corp. v. United States — the U.S. arm of a Japanese trading house.
That single fact explains why this is not a foreign concern. A factory, an overseas buyer, and a trading company in between: the structure that is entirely ordinary in Japanese manufacturing is precisely the setting where this question arises.
The two previous pieces covered moving origin and classification by shipping assembled versus as parts and designing the classification itself. Of the three elements CBP uses to calculate duty — HTS code, country of origin and declared value — the remaining one is declared value.
Which price do you declare?
The typical structure:
[Factory] ──sells at ¥800,000──▶ [Trading house] ──sells at ¥1,000,000──▶ [U.S. importer]
The factory sells to the trading house at ¥800,000; the trading house sells to the U.S. importer at ¥1,000,000. The same goods arrive in the United States.
Which price does the duty attach to?
The intuitive answer is the ¥1,000,000 the importer paid, and that is indeed CBP's starting assumption. But where certain conditions are met, the first sale — the ¥800,000 — can be declared as the dutiable value. That is first sale.
At an assumed 25%, the ¥1,000,000 base gives ¥250,000 and the ¥800,000 base gives ¥200,000. ¥50,000 on one transaction, and it compounds with volume. The middleman's margin drops out of the dutiable base.
What Nissho Iwai established
The case is Nissho Iwai American Corp. v. United States, 982 F.2d 505 (Fed. Cir. 1992).
The court accepted that in a structure where a factory sells to a middleman and the middleman sells to an importer, the manufacturer's price may be used to determine transaction value.
For the three-tier structure, the conditions were framed as:
- The goods are clearly destined for export to the United States
- The manufacturer and the middleman deal with each other at arm's length
- There are no non-market influences affecting the legitimacy of the sale price
Replace siloed classification work with AI.
METI's FY2024 data shows 52% of foreign exchange law violations stem from classification errors. Download the TRAFEED product catalog covering features and rollout.
The three requirements
In practice the requirements resolve to:
| Requirement | What it means |
|---|---|
| ① A bona fide sale | Title and risk actually transfer. A paper transaction is not enough |
| ② A sale for exportation to the U.S. | The U.S. destination is clear at that point |
| ③ Price not influenced by the relationship | The relationship between the parties has not distorted the price (arm's length) |
The one that trips people up is ①. Where a trading house is simply passing paperwork through, with neither title nor risk genuinely moving, there is no bona fide sale. Put the other way: if the trading house really is carrying inventory risk and credit risk, that reality can be shown.
The burden sits with the importer
This is the heavy part in practice.
CBP presumes that the price paid by the importer is the basis for transaction value (Treasury Decision 96-87). Using first sale means displacing that presumption, and the burden of doing so is the importer's.
Further, where a price from earlier than the last sale is used, that must be declared at entry. Quietly declaring the lower figure is not an option.
And CBP's verification has reportedly tightened in recent years. As duty rates rise, the incentive to use the technique rises with them — and so, predictably, does the scrutiny.
The documentation that gets asked for:
- The sales contract, purchase orders and invoices between factory and middleman
- Terms showing title and risk transfer (Incoterms, insurance, acceptance conditions)
- Payment records — money actually moving
- Evidence of U.S. destination (specified consignee, product specifications)
- Documentation of any relationship between the parties, and of price reasonableness
All of it is the kind of thing that is hardest to assemble after the fact. From the moment you decide to use first sale, it has to accumulate transaction by transaction.
The rule itself is unstable
This needs saying plainly.
Members of the Senate Finance Committee have moved to eliminate the first sale principle, valuing goods on the last sale instead.
If that becomes law, the technique ends. Which means fixing your supply chain structure on the assumption that first sale survives is risky.
A realistic posture:
- Use it while it is available — but structure contracts and logistics so they stand on their own if it goes
- Model the impact of repeal now. How much does the burden rise, and does it need to pass through to price
- Be able to justify the middleman's role for reasons other than duty. Inventory risk, quality assurance, credit — if the trading house functions are real, the structure survives a rule change
That third point matters most. A structure that exists only for first sale becomes meaningless the moment the rule changes. A trading house that genuinely performs its functions has value independent of customs law.
What this means for Japanese companies
Two positions.
When you are the factory. If you ship to the U.S. through a trading house and the U.S. importer wants to use first sale, they will ask for your sale price documentation — contracts, invoices, payment records. "Do we hand over our pricing for a customer's duty position?" is a real question, but it touches total supply chain cost, and you are not outside it.
When you are the middleman. If you carry trading house functions, the question is whether you can be shown as a genuine party to a bona fide sale. Do you actually bear title and risk, and do the documents show it?
In both positions, what you need is the same: the ability to explain the reality of the transaction on paper.
What three articles add up to
Across this series we have taken the three elements one at a time.
| Element | How it moves | The line |
|---|---|---|
| HTS code | Design the classification | A change that means something as a product, or decoration for the classification |
| Country of origin | Design where the work happens | A substantial transformation, or just a routing |
| Declared value | Use first sale | A bona fide sale, or paperwork passing through |
All three have the same structure.
If the reality is there, it is design. If it is not, it is disguise.
The rules say "in this situation, this treatment applies," and building a business around those rules is ordinary commercial diligence. What is prohibited is declaring that you meet a rule you do not meet.
And whether you can explain that reality afterwards decides everything. CBP asks not for the conclusion but for the basis and the record. DOJ's Trade Fraud Task Force, past $1 billion as of July 2026, lists transshipment, misclassification, undervaluation and false origin — which is to say, the three elements, each where declaration and reality diverge.
Handling it in practice
- Once you decide to use it, start keeping the documentation from that moment. It does not assemble afterwards
- Meet the declaration obligation at entry when using a price earlier than the last sale
- Consider an advance ruling. Japan Customs advance rulings cover customs value as well
- Build in the repeal scenario. Do not fix the structure on the rule surviving
- Involve a customs broker. Valuation is customs professionals' territory. Before applying any of this to your transactions, run it through a broker and, where appropriate, an advance ruling
Seen from the export control side
First sale asks who holds title and risk. Export control asks a related question: who is the substantive party to the transaction, and who is the end user?
Awkwardly, the two look at the same documents and reach different answers. A middleman can be the genuine buyer for customs purposes while the end user still has to be confirmed separately for export control. "It goes through a trading house, so screening is their job" does not follow.
TRAFEED covers the export control side: how to confirm the end user in a multi-tier transaction, whether a counterparty appears on the control lists of the jurisdictions involved, and how to keep the evidence behind those calls. If a lot of your business runs through trading houses and the boundary of responsibility feels unclear, the three-minute self-check is a place to start.
Key takeaways
- First sale allows the U.S. dutiable value in a factory → middleman → importer structure to be based on the first sale
- The leading case is Nissho Iwai American Corp. v. United States, 982 F.2d 505 (Fed. Cir. 1992) — named for a Japanese trading house
- Three requirements: a bona fide sale (title and risk transfer) / a sale for exportation to the U.S. / a price not influenced by the relationship
- The burden sits with the importer (Treasury Decision 96-87), a price earlier than the last sale must be declared at entry, and verification has reportedly tightened
- A bill in Congress would eliminate the principle. Do not fix the structure on its survival
- All three elements share a structure: if the reality is there it is design, if not it is disguise
- Valuation is customs professionals' territory. Work through a customs broker and the advance ruling systems
For export control questions, get in touch. Tariffs and clearance themselves belong to customs brokers, but the adjacent ground we can map together.
Sources
- Nissho Iwai American Corp. v. United States, 982 F.2d 505 (Fed. Cir. 1992) — U.S. Court of Appeals for the Federal Circuit
- H005222: Transaction value; Nissho Iwai; Sale for Export — U.S. Customs and Border Protection — https://rulings.cbp.gov/ruling/H005222
- Treasury Decision 96-87 — U.S. Customs and Border Protection
- CROSS (Customs Rulings Online Search System) — U.S. Customs and Border Protection — https://rulings.cbp.gov/
- A Resource Guide to Trade Fraud Enforcement — U.S. Department of Justice — July 2026 — https://justice.gov/fraud/media/1452331/dl?inline=
- Advance ruling system — Japan Customs — https://www.customs.go.jp/
※ The status of the bill to eliminate first sale is in flux. Check the current legislative position before applying any of this, and work through a licensed customs broker and, where appropriate, an advance ruling. Content reflects publicly available information confirmed as of 2 August 2026.